DSCR loans
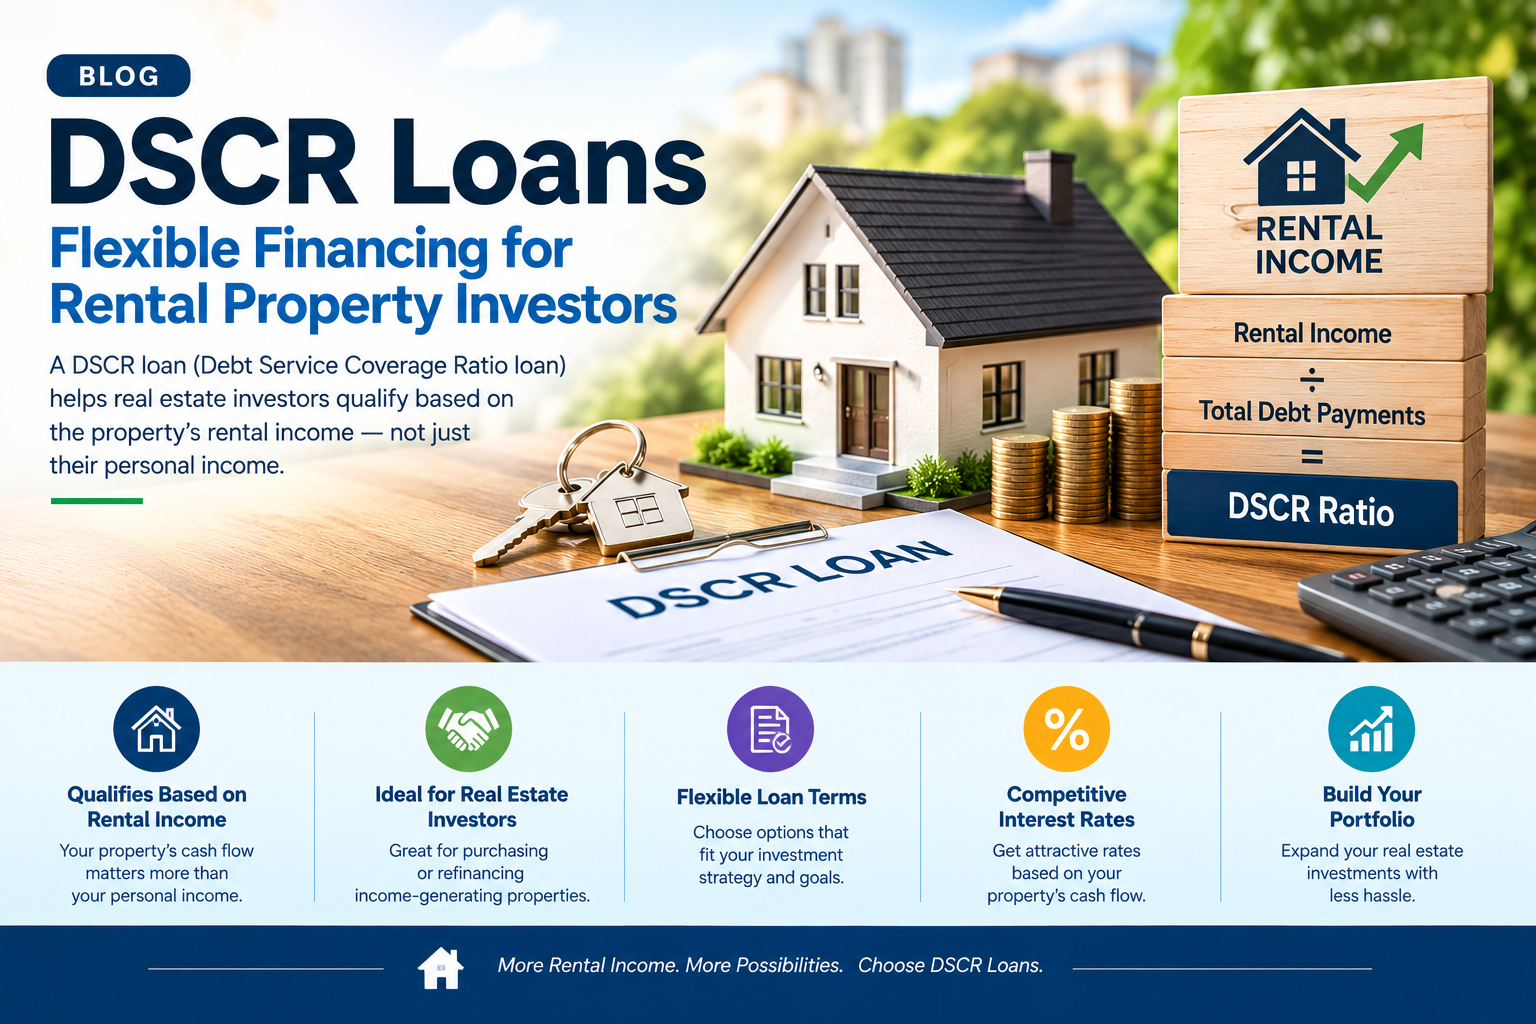
DSCR Loans: A Complete Guide to Real Estate Investment Financing
Investing in rental properties can be a great way to build long-term wealth and generate passive income. However, getting traditional mortgage approval can sometimes be challenging for real estate investors, especially when lenders require extensive personal income documentation. This is where DSCR loans can provide an alternative financing solution.
A Debt Service Coverage Ratio (DSCR) loan is designed primarily for real estate investors who want to qualify for financing based on the income generated by an investment property rather than relying mainly on their personal employment income.
What Are DSCR Loans?
DSCR loans are mortgage financing options that evaluate whether a property's rental income is sufficient to cover its monthly debt obligations. Instead of focusing primarily on the borrower's personal income, lenders generally examine the property's cash flow.
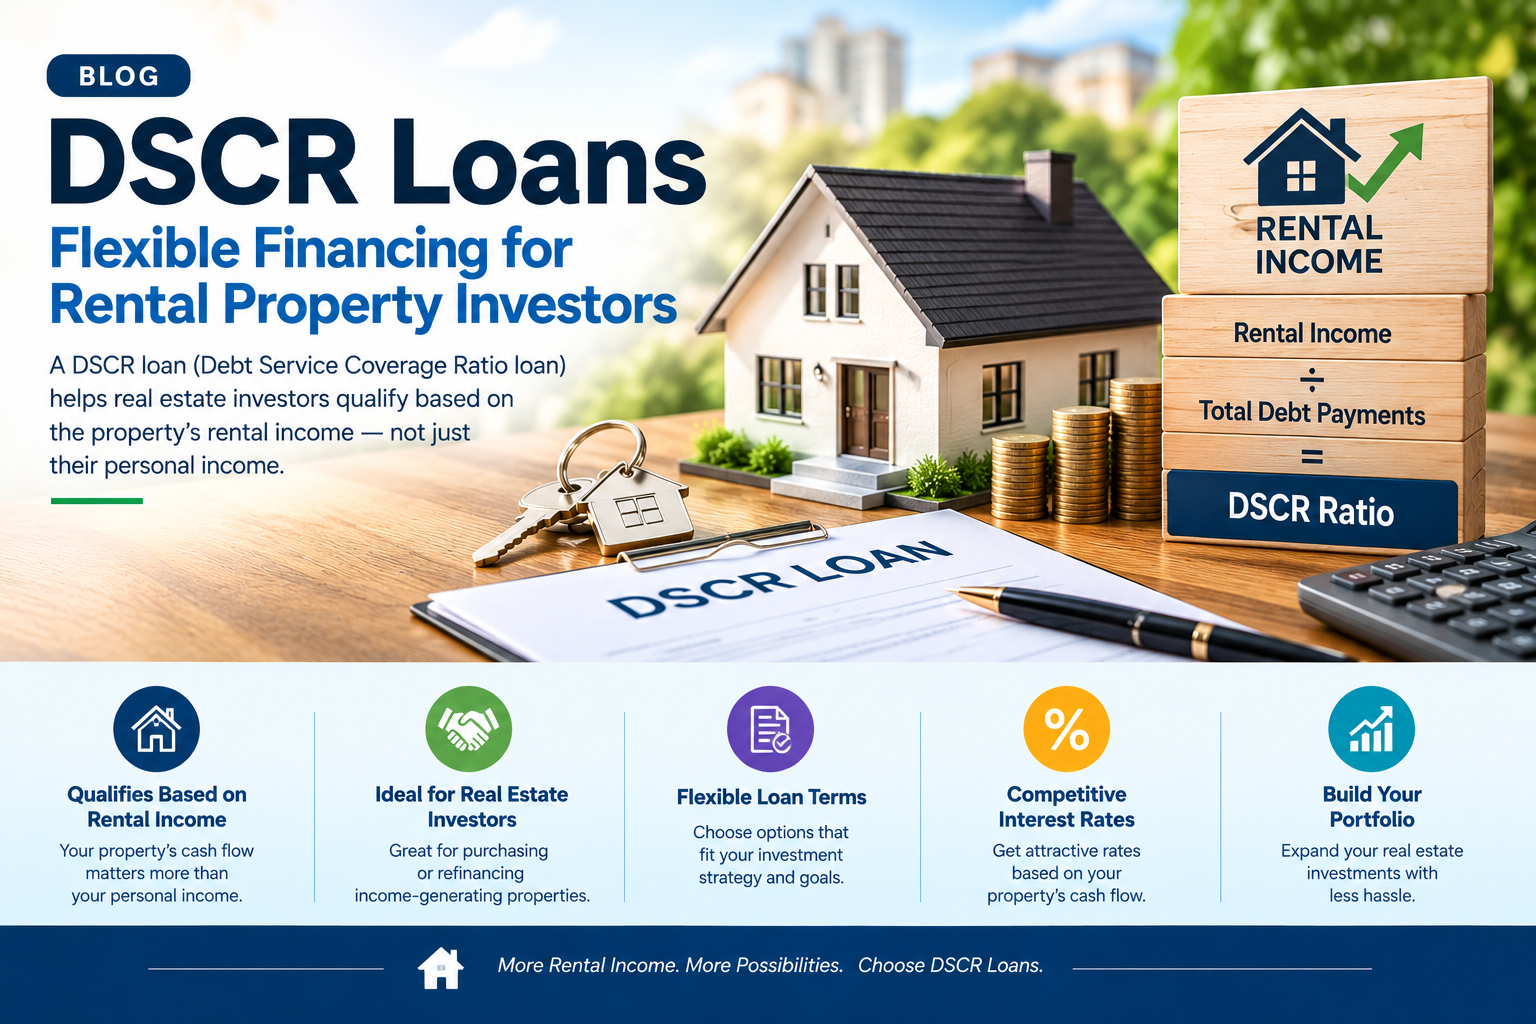
The Debt Service Coverage Ratio measures the relationship between a property's net operating income and its debt payments.
For example, if a rental property generates $3,000 in monthly qualifying income and its monthly mortgage payment is $2,500, the DSCR is:
A ratio of 1.20 means the property generates 20% more income than the monthly debt obligation used in this example.
How Do DSCR Loans Work?
DSCR loans work differently from many traditional home mortgages. The lender evaluates the property's income potential to determine whether it can support the loan payments.
The general process includes:
-
Property Evaluation: The lender reviews the investment property's value and rental income potential.
-
Income Calculation: Qualifying rental income is compared with eligible property expenses and debt obligations according to the loan program.
-
DSCR Calculation: The lender calculates the property's debt service coverage ratio.
-
Loan Approval: The lender considers the DSCR along with credit history, down payment, property type, and other eligibility requirements.
Requirements vary between lenders, so investors should compare loan programs carefully.
Benefits of DSCR Loans for Real Estate Investors
DSCR loans offer several advantages for eligible property investors.
1. Property Income-Based Qualification
One of the biggest advantages is that qualification focuses on the investment property's cash flow rather than relying primarily on personal employment income.
2. Useful for Self-Employed Investors
Self-employed individuals and business owners may find DSCR financing helpful because traditional income documentation can sometimes be complicated.
3. Investment Property Financing
These loans are generally designed for income-producing residential investment properties, including eligible rental homes and certain multifamily properties.
4. Opportunity to Expand a Property Portfolio
Investors may use DSCR financing to purchase additional rental properties, subject to lender requirements and their overall financial position.
5. Flexible Documentation Options
Some DSCR programs require less traditional personal income documentation than conventional mortgage programs.
Who Should Consider DSCR Loans?
DSCR loans may be worth considering for:
-
Real estate investors purchasing rental properties.
-
Self-employed property investors.
-
Individuals building a rental property portfolio.
-
Investors with multiple income-producing properties.
-
Borrowers whose personal tax returns do not fully reflect their property's rental income potential.
However, these loans are not suitable for every borrower or property. Reviewing the lender's requirements is essential.
DSCR Loans vs. Traditional Mortgage Loans
The main difference between DSCR loans and traditional mortgages is how lenders evaluate repayment ability.
Traditional mortgages generally place significant emphasis on the borrower's personal income, employment, credit, and debt-to-income ratio.
DSCR loans primarily evaluate the investment property's income relative to its debt obligations. However, lenders may still review personal credit, assets, reserves, and other financial information.
Important Factors to Consider Before Applying
Before choosing DSCR financing, investors should review the following:
-
Interest Rates: Compare rates and understand whether they are fixed or adjustable.
-
Down Payment: Check the minimum down payment required by the lender.
-
Credit Score: Review the lender's minimum credit requirements.
-
Rental Income: Confirm how the lender calculates qualifying rental income.
-
Closing Costs: Understand all fees and additional expenses.
-
Prepayment Penalties: Check whether paying off the loan early involves additional charges.
Carefully reviewing these details can help investors understand the total cost of financing.
Conclusion
DSCR loans can be a valuable financing option for real estate investors who want to qualify based on the income generated by their investment properties. By focusing on rental cash flow, these loans provide an alternative to traditional mortgage qualification methods.
Whether you are purchasing your first rental property or expanding an existing investment portfolio, comparing DSCR loan programs and understanding their requirements can help you make a better financing decision.
Frequently Asked Questions (FAQs)
1. What does DSCR stand for in mortgage lending?
DSCR stands for Debt Service Coverage Ratio. It measures a property's income in relation to its debt obligations.
2. What is a good DSCR ratio for a loan?
A DSCR of 1.0 means qualifying property income equals the debt obligation. Some lenders prefer a ratio above 1.0, although requirements vary by loan program.
3. Can I get a DSCR loan without personal income verification?
Some DSCR programs do not require traditional personal income verification, but lenders may still review credit, assets, reserves, and other financial details.
4. Can DSCR loans be used for rental properties?
Yes. DSCR loans are primarily designed for eligible income-producing investment properties, including residential rental properties.
5. Are DSCR loans suitable for first-time real estate investors?
They may be suitable for first-time investors who meet the lender's property, credit, down payment, and other eligibility requirements.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek